
Buying your first home?
Whether you're saving for a deposit, working out what you can borrow or ready to start house hunting, Aurevia helps you understand your home loan options and navigate your first purchase.
How we help you buy your first home.
Understand what you can borrow
We'll assess your financial situation to help you understand your borrowing capacity, estimated repayments and any first home buyer schemes you may qualify for. We can also arrange pre-approval with a suitable lender, giving you a clearer budget before you start looking for your first home.
Find the right loan for your first home
We'll compare home loans from our panel of lenders, assessing interest rates, fees, features and eligibility requirements. We'll explain the differences, answer your questions and recommend a suitable loan for your circumstances, so you can make an informed decision rather than relying on a single bank's options.
Get support through to settlement
We'll prepare and manage your loan application, communicate with your lender and coordinate with your conveyancer as settlement approaches. From submitting your application to receiving your keys, we'll help you understand what's required, manage the finance process and keep you informed along the way.
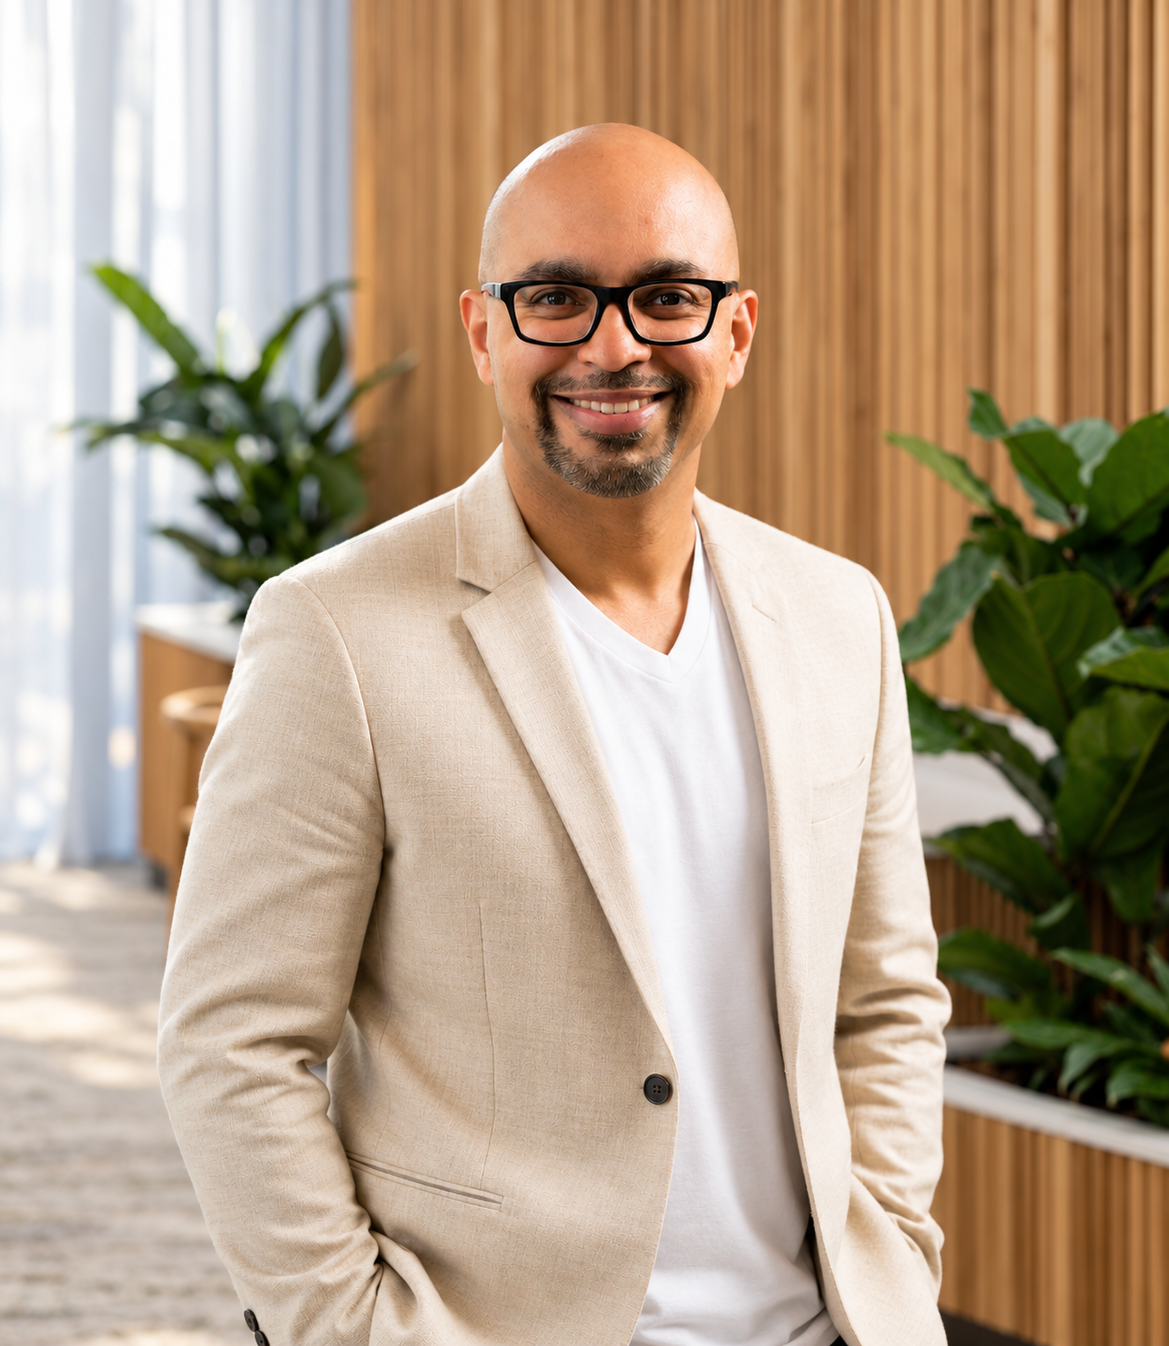
Meet your partner in finance, RK.
You've worked hard to get to this point. Buying your first home is a big milestone, and having the right guidance can make all the difference.
RK takes the time to understand your circumstances, explain your options and help you make informed decisions about your first home loan.
From understanding what you can borrow to choosing a suitable loan and navigating the process through to settlement, he'll be there to guide you every step of the way.
RK is available 7am to 7pm, 7 days a week.
Talk to RK directly on 0412 517 237
Help with the cost of your first home.
5% deposit, no LMI
The Australian Government 5% Deposit Scheme allows eligible buyers to purchase with a 5% deposit without paying lenders mortgage insurance. There are no income caps, but property price limits and eligibility requirements apply.
Stamp duty concessions
First home buyers may qualify for stamp duty discounts or exemptions, depending on where they're purchasing and the property's value. We'll help you understand which concessions may apply.
Saving through super
The First Home Super Saver Scheme lets eligible buyers save towards a deposit through voluntary super contributions, up to $15,000 per year and $50,000 in total. Consider speaking with a qualified financial adviser about whether it suits you.
Let's talk about your next move.
Whether you're ready to start house hunting or still working out what you can afford, RK can help you understand your borrowing options and the steps involved in buying your first home.
Frequently Asked Questions.
-
The deposit you'll need depends on the property price, your financial circumstances and the lender's requirements. While a 20% deposit can help you avoid lenders mortgage insurance, some buyers may qualify for a home loan with a smaller deposit. Government schemes may also help eligible first home buyers purchase with as little as 5% deposit.
-
Your borrowing capacity depends on factors including your income, living expenses, existing debts, credit history and the lender's assessment criteria. We'll review your financial situation, compare suitable lending options and help you understand how much you may be able to borrow and what your repayments could look like.
-
Pre-approval is an indication from a lender of how much they may be willing to lend, subject to conditions and final assessment. While it isn't compulsory, having pre-approval before you start house hunting can help you establish a realistic budget and understand your borrowing position. It isn't a guarantee of final loan approval.
-
Depending on your eligibility and where you're buying, you may qualify for assistance such as the Australian Government 5% Deposit Scheme, stamp duty exemptions or concessions, and the First Home Super Saver Scheme. Each has different rules and requirements. We'll help you understand which options may be relevant to your purchase.
-
Beyond your deposit, you may need to budget for stamp duty, conveyancing or legal fees, building and pest inspections, lender fees, insurance and moving expenses. Some buyers may qualify for stamp duty concessions or exemptions. We'll help you understand the likely costs so you can plan your purchase with fewer surprises.
-
A bank can generally offer you its own home loan products. A mortgage broker can compare options from a panel of lenders, helping you assess interest rates, fees, features and eligibility requirements. We'll explain your options, recommend a suitable loan and assist with the application process through to settlement.