
New to Australia and looking to buy?
Whether you've recently arrived or are settling into life in Australia, Aurevia helps you understand your home loan options and navigate the buying process.
How we help new Australian residents.
Permanent residents
Ready to buy a home in Australia? We'll help you understand your borrowing capacity, lender requirements and home loan options based on your income and residency circumstances.
Temporary visa holders
Your visa type can affect which lenders and loan products are available. We'll help you explore suitable options and understand the conditions that may apply to your application.
Returning Australians
Moving back to Australia after living overseas? We'll help you understand how lenders may assess overseas income, employment history and existing financial commitments.
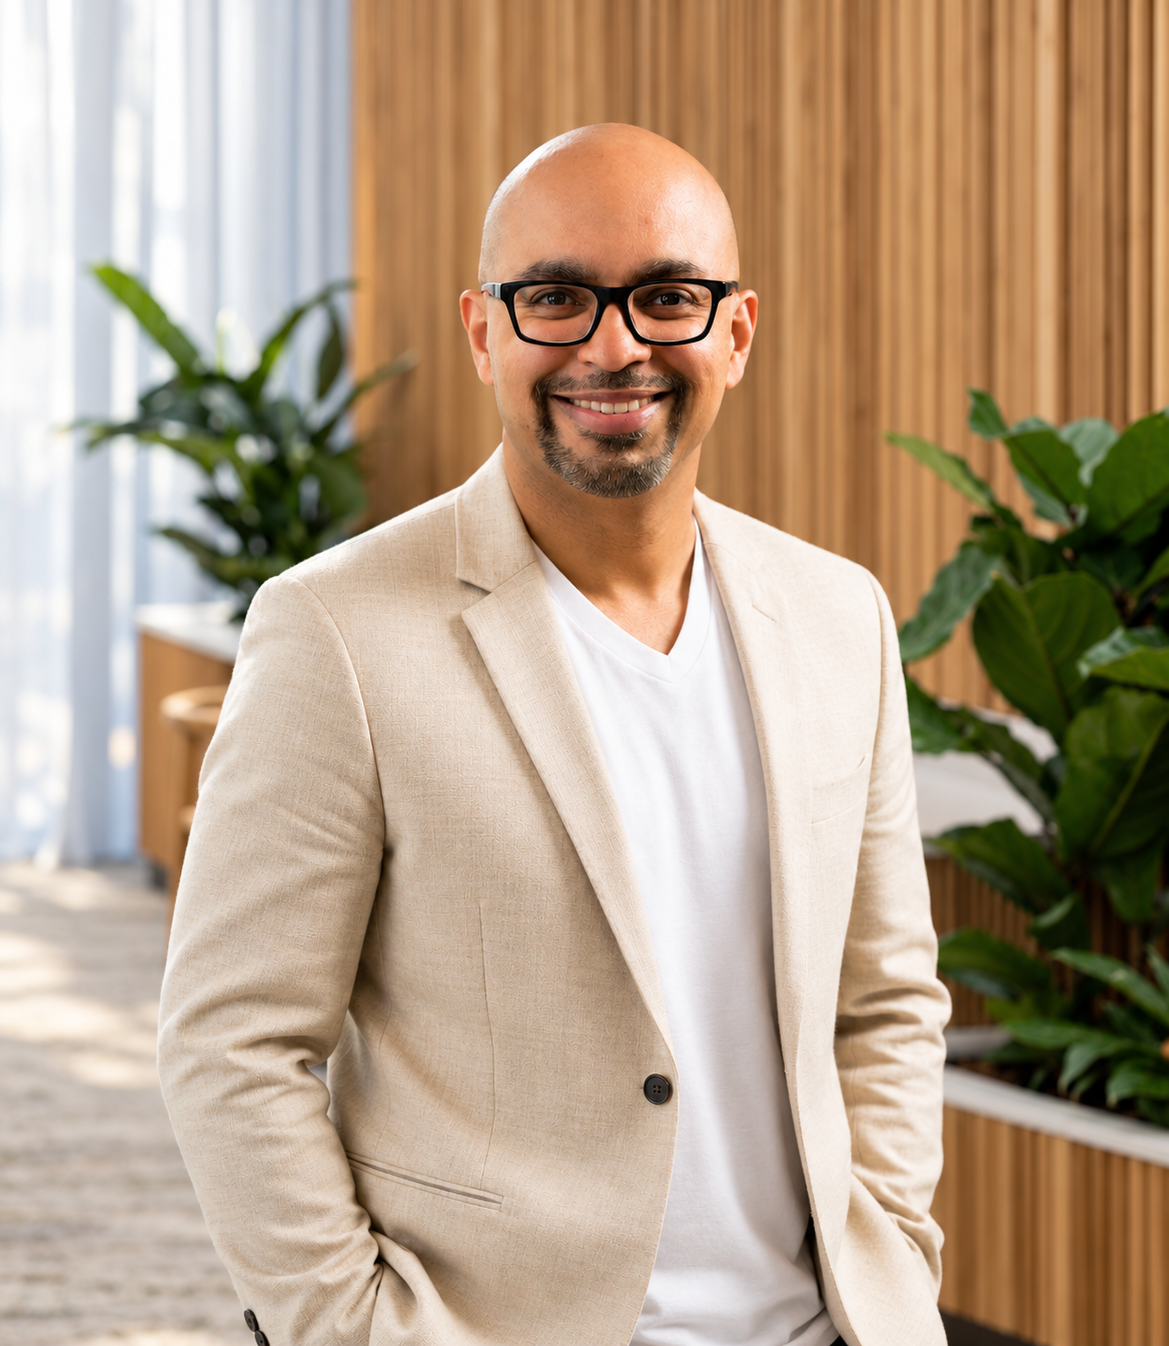
Meet your partner in finance, RK.
Buying a home in Australia can feel complicated when you're unfamiliar with the local lending system. Different visa requirements, financial documentation and lender policies can make it difficult to know where to begin.
RK takes the time to understand your residency status, income arrangements and property plans before explaining which home loan options may be available to you.
From understanding lender requirements to preparing your application and navigating the approval process, you'll work directly with RK through to settlement and beyond.
RK is available 7am to 7pm, 7 days a week.
Talk to RK directly on 0412 517 237
What matters when buying in Australia.
Your residency and visa status
Your residency status can influence lender eligibility, deposit requirements and borrowing options. Different lenders have different policies for permanent residents and temporary visa holders.
Your income and financial history
Lenders may assess Australian and overseas income differently. Your employment history, credit record and supporting documentation can also affect which loan options are available.
Your deposit and purchase costs
Deposit requirements can vary depending on your residency status and the lender. You may also need to consider stamp duty, legal fees and any additional purchasing restrictions or charges that apply to your circumstances.
Let's talk about buying in Australia.
Whether you've recently arrived, are planning a move or are ready to purchase your first Australian property, RK can help you understand your lending options and what steps to take next.
Frequently Asked Questions.
-
Yes, depending on your residency status, income, financial circumstances and the lender's requirements. Some lenders are more accommodating of applicants with limited Australian employment or credit history. We'll help you understand which options may be available.
-
Some temporary visa holders may be eligible for home loans, depending on their visa type, employment circumstances and the lender's policies. Additional deposit requirements or restrictions may apply. Property purchase eligibility is also subject to Australian foreign investment rules.
-
The deposit required depends on the lender, your residency status, property type and financial circumstances. Some borrowers may qualify for loans with smaller deposits, while others may be required to contribute more. Additional purchasing costs should also be considered.
-
Some lenders may consider overseas income, although eligibility depends on the country, currency, income type and supporting documentation. Lenders may apply different assessment methods or restrictions to foreign income.
-
Not necessarily. A limited Australian credit history doesn't automatically prevent you from applying. Lenders will assess your overall financial position and may require additional evidence of income, savings and existing financial commitments.
-
There can be. Depending on your residency status and the property, you may need foreign investment approval and may face additional taxes, duties or purchasing restrictions. Rules differ by buyer category and jurisdiction, so it's important to confirm your eligibility and obligations before committing to a purchase.